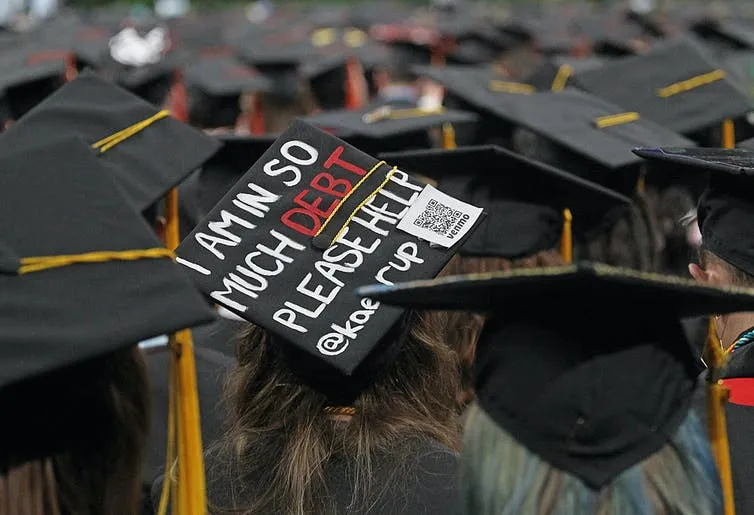
Patience Pays. DEBT forgiveness came with a tax bill
My Student Loans Were Forgiven After 25 Years. Then Came the Tax Bill.
Twenty-five years. That’s how long I carried my student loans. Twenty-five years of payments, paperwork, and waiting. This year, my student loans were finally forgiven. Alhamdulillah.
I sat with that for a moment. The DEBT that once made me unbankable was gone.
Then yesterday, I got the shock: a tax bill on the DEBT that was forgiven.
When DEBT Becomes “Income”
Here’s what most people don’t know. Starting in 2026, student loan forgiveness under income-driven repayment plans is taxable income again. The pandemic-era protection ended on December 31, 2025.
So the $67,000 I no longer owe is now counted as money I earned. On paper, that DEBT pushes me over six figures of income for 2026, and my tax liability goes up with it.
A debt I paid on for 25 years is now being taxed like a raise.
I could have panicked. Instead, I picked up the phone.
Wealth Is a Team Sport
I called my accountant right away. I believe two brains are better than one, and half of problem solving is asking the right question.
In 30 seconds, my accountant laid out a plan that works for low-income families with young children who qualify for the Earned Income Tax Credit. These are the families I care about most:
File your 2026 taxes and see the real number. Don’t guess. Know your liability.
Expect no refund in year one. The forgiven amount raises your income so much that the Earned Income Tax Credit you usually count on will likely disappear for that year.
Set up an IRS payment plan. Make a small, affordable payment every single month for the full year. Don’t miss a payment like EVER.
File again in 2027. When your income goes back to normal, your EITC returns, and the IRS applies that refund to the remaining balance.
It’s a two-year plan. It only works for the family that is disciplined. But discipline is the whole game.
The Pebble and the Mountain
The forgiveness was the goal. The tax bill is a small pebble in the grand plan.
Twenty-five years ago, that DEBT was a mountain. Today it’s a pebble I can walk over with a plan, a partner, and patience.
For me, this is an opportunity to:
Max out my charitable giving and the deductions that come with it
Defer taxable income into retirement accounts like an IRA or 401(k), in sha Allah
The same event that looks like a setback is pushing me to plan more intentionally than ever.
Before You Panic, Ask
If your loans were forgiven this year, don’t let the tax bill steal your joy. Get your numbers, get a professional on your team, and ask about every option. Some families may qualify to exclude part or all of the forgiven amount if they were insolvent, meaning they owed more than they owned, right before the forgiveness.
Patience paid off for me. A plan will pay off for you.
Reflection: When a blessing arrives with a bill attached, do you see the bill, or do you see the blessing and start planning?
This is not tax advice as wealth building series is NOT an accounting firm.
This post shares my personal experience and is not tax advice. Tax rules depend on your situation, so talk with a qualified tax professional before acting.
